Key points
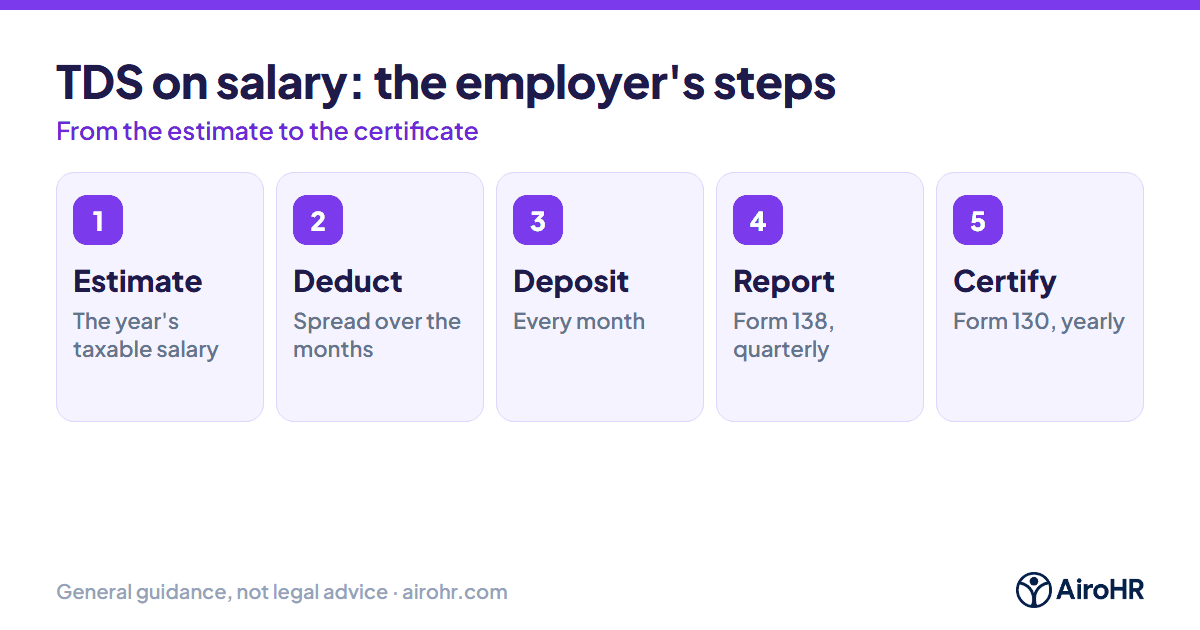
- The employer estimates each employee's taxable salary for the whole year and spreads the tax across the remaining months.
- The new tax regime is the default; employees must opt for the old regime if they want it.
- Declarations drive TDS during the year; proofs decide the final months' deduction.
- Tax deducted is deposited monthly, reported in quarterly TDS statements (Form 138, formerly Form 24Q) and certified to employees in Form 130 (formerly Form 16).
Why employers deduct tax from salary
Salary is taxed at source: instead of the employee paying all their income tax at year-end, the employer deducts it every month and pays it to the government. This is TDS — tax deducted at source. The employer acts as a collection point, and failure to deduct or deposit correctly makes the employer liable for the shortfall, along with interest and penalties.
Unlike PF or ESI, TDS on salary is not a fixed percentage. It depends on the employee's total expected income for the year, the regime they choose and the deductions they are entitled to.
Step 1: estimate annual taxable salary
At the start of the year (and whenever salary changes), payroll projects each employee's salary for the full tax year (1 April to 31 March):
- Gross salary — basic, allowances, bonus, overtime, perquisites and any arrears expected in the year.
- Less exemptions — for example, parts of certain allowances where the regime allows them.
- Less the standard deduction — a flat deduction for salaried employees, available without proof.
- Less deductions — investments and payments the employee has declared, where the chosen regime allows them.
- Add other income the employee chooses to report to the employer (for example, from a previous employer in the same year).
The tax on this projected income, after any rebate and including cess, is the annual tax liability. The employer then deducts it in roughly equal instalments over the remaining months of the year.
Recalculating during the year
The projection is not a one-time exercise. Increments, bonuses, loss-of-pay months, a change of regime, new declarations or a mid-year joining all change the annual estimate. Good practice is to recompute every month: annual liability minus tax already deducted, divided by months remaining.
Step 2: old regime or new regime
| New regime | Old regime | |
|---|---|---|
| Status | Default — applies unless the employee opts out | Must be chosen by the employee |
| Slab rates | Lower rates, more slabs | Higher rates, fewer slabs |
| Exemptions & deductions | Very limited; standard deduction allowed | Most exemptions and investment deductions available |
| Who it usually suits | Employees with few investments or tax-saving expenses | Employees with significant HRA, home loan interest or eligible investments |
For TDS purposes, the employer collects the employee's regime choice at the start of the year. The employee's final choice when filing their own return can differ, subject to the rules that apply to them — the employer's job is to deduct correctly based on what was declared.
Tax declarations and TDS, inside payroll
In AiroHR, HR enters each employee's monthly TDS and every payroll run deducts it (never more than the month's pay; any balance carries to the next month). Employees declare their regime and investments in the employee portal and can compare the two regimes there.
Payroll software Request free trialStep 3: investment declarations and proofs
Most employers run a two-stage process:
- Declaration window (start of year): employees declare planned investments, rent paid, home loan interest and similar items. TDS for the first part of the year is based on these declarations.
- Proof window (towards year-end): employees submit rent receipts, investment statements, insurance premium receipts and loan certificates. Anything not proved is removed from the calculation, and the remaining months' TDS goes up to cover the difference.
Set clear deadlines and communicate them early. The most common complaint in payroll — a sharp jump in TDS in January to March — is almost always caused by missing proofs discovered late.
Step 4: deposit, report and certify
| Obligation | Frequency | What it involves |
|---|---|---|
| Deposit TDS | Monthly | Pay the tax deducted from salaries to the government by the prescribed due date, using your TAN. |
| TDS statement (Form 138) | Quarterly | File the salary TDS statement listing each employee's PAN, salary and tax deducted and deposited. |
| Form 130 (formerly Form 16) | Yearly, by 15 June after the tax year | Issue each employee the salary TDS certificate generated from TRACES, with the salary details annexure. |
Two identifiers matter: the employer's TAN, which every deposit and statement uses, and each employee's PAN. Where an employee's PAN is missing or invalid, higher deduction rules can apply, and the tax credit may not reach the employee — so collect and verify PAN at joining.
Common TDS mistakes
- Deducting a flat percentage every month instead of projecting annual income.
- Not recalculating after an increment, bonus or a change of regime.
- Ignoring income from a previous employer that the employee has disclosed for the same year.
- Mismatched PAN or salary between the Form 138 statement and Form 130.
- Using rates, limits or form names from the old Act after 1 April 2026 without checking current notifications.
TDS is one of four monthly statutory deductions. See our guides to ESI calculation and Professional Tax in Karnataka; PT paid is deductible from salary only for employees on the old regime.
PF, ESI, PT and TDS in every payroll run
AiroHR calculates PF, ESI and PT once your rules are set up, deducts the monthly TDS you set, keeps an audit trail of every change and sends payslips on email and WhatsApp. From ₹49 per employee per month.
PF & ESI software See pricingOfficial sources
- Section 392, Income-tax Act, 2025: salary — Income Tax Department
- Form No. 130: certificate of tax deducted at source on salary — Income Tax Department
Work it out, then stay up to date
Use the free salary slip generator, or get each month's PF, ESI, PT and TDS dates by email with free compliance alerts.
Related guides
This article is general guidance, not legal or tax advice. Income-tax law, rates and forms change — always check the latest CBDT and Income Tax Department notifications or consult a tax professional. Last reviewed: 15 October 2026.